Summary
Long-term care insurance often covers assisted living when a licensed professional certifies the need for help with daily tasks or cognitive impairment. Understanding your policy's benefit amount, elimination period, and coverage definition helps you maximize reimbursement and plan finances accurately.
- Most policies cover assisted living's monthly fee once you meet the care requirement, usually two or more activities of daily living
- Elimination periods typically run 30–90 days; confirm whether yours counts calendar days or paid-care days to plan out-of-pocket costs
- File your claim before or right after moving in; late filings can forfeit reimbursements for care you've already received
- Compare your daily benefit amount to the community's monthly fee to see what gap savings, Social Security, or pensions need to cover
- Ask whether the insurer pays the community directly or reimburses you, and verify the community meets your policy's state licensure definition
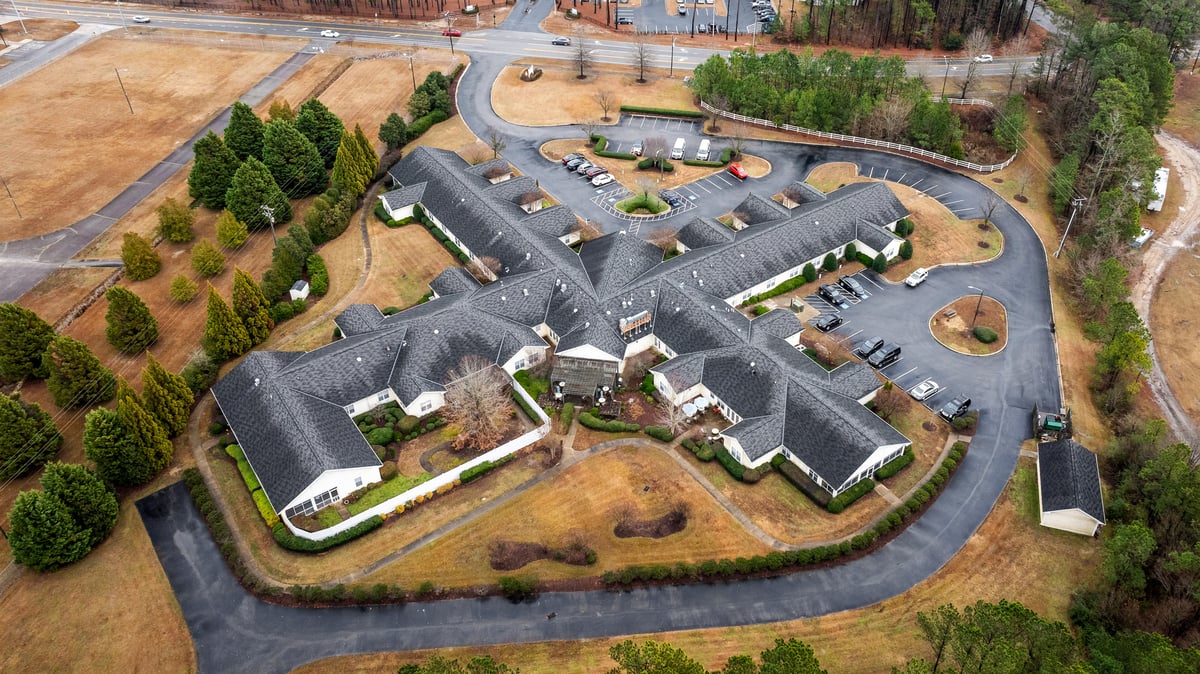
Somewhere in a filing cabinet is the long-term care policy your parent bought twenty years ago, and right now it might be the most valuable piece of paper in the house. Does long-term care insurance cover assisted living? In most cases, yes. The harder questions are how much, starting when, and what you have to do to collect. At TerraBella Fayetteville in Fayetteville, NC, we help families work through long-term care insurance for assisted living every month, and the process is more manageable than the paperwork makes it look.
What Your Policy Probably Covers
Policies differ, but most written in the last few decades name assisted living as a covered setting. Benefits typically start when a licensed professional certifies that the policyholder needs help with at least two ADLs, the insurance term for basic self-care tasks like bathing, dressing, and transferring, or a cognitive impairment that requires supervision. The policy will also set an elimination period, a stretch of 30 to 90 days when the family pays out of pocket before benefits begin. Pull out the paperwork and find three things:
- The daily or monthly benefit amount, and whether it has inflation protection
- The elimination period and whether it’s counted in calendar days or days of paid care
- The policy’s definition of a qualifying community, which usually requires state licensure
What Does Long-Term Care Insurance Pay For?
So what does long-term care insurance pay for once benefits start? In an assisted living community, the benefit usually applies to the monthly fee as a whole, which for Assisted Living at TerraBella Fayetteville covers:
- Personal care, including help with bathing, grooming, and medication management
- Three chef-prepared meals a day, weekly housekeeping, and laundry
- Scheduled transportation to appointments at Cape Fear Valley Medical Center and around Fayetteville
- Apartment maintenance and the programs on the community calendar
Most policies pay a set daily rate. If the monthly fee is higher than the benefit, the family covers the difference, so it helps to compare the benefit against the Red Maple suite and White Oak one-bedroom pricing early.
How to Use Long-Term Care Insurance Step by Step
Knowing how to use long-term care insurance saves weeks and sometimes thousands of dollars. The sequence looks like this:
- Call the insurer before the move and ask what documentation starts a claim
- Schedule the care assessment, usually done by a nurse the insurer arranges or approves
- Confirm the community meets the policy’s licensing definition, and get it in writing
- Submit the claim and the community’s service plan, then track the elimination period
- Ask whether the insurer will pay the community directly or reimburse you
Our team at TerraBella Fayetteville has done this many times and can provide the service plan, invoices, and licensure details insurers ask for.
Do the Math Before You Choose
Using LTC insurance for senior living works best when you know the gap in advance. A policy with a $150 daily benefit pays roughly $4,500 a month. Set that beside the community’s monthly fee, and you’ll see what’s left for savings, Social Security, or a pension to cover. Inflation protection matters here, since a benefit that grows each year keeps pace with fee increases over a stay that often lasts several years. If the numbers are close, ask about the one-bedroom versus the suite; the difference may be exactly what the policy covers.
Get Every Dollar You’re Owed
File as soon as the move is scheduled, not after the first bill. Late filings can forfeit reimbursements for care already received. Keep copies of everything, note the name and date of every call, and ask the community’s business office to send records directly to the insurer when possible. Finally, separate what the policy pays for from what you choose to add. The core fee is assisted living covered by LTC insurance in most policies; a salon visit or a special outing is a personal choice, and budgeting for both keeps surprises off the statement.
A few questions families ask us:
Does the elimination period start when my parent moves in? Usually it starts when a licensed professional certifies the need for care, which can happen before the move. Ask your insurer.
Will the policy cover GLOW® Memory Care if needs change? Most policies that cover assisted living also cover memory care in a licensed community, often under the cognitive impairment trigger. Check the policy language.
What if my parent’s policy was issued before assisted living was common? Some older policies name only skilled nursing settings. Call the insurer; many have updated definitions, and an agent can tell you where you stand.
Put the Policy to Work
A long-term care policy is only valuable once a claim is filed well, and that takes a little planning and a community willing to help with the paperwork. Bring your parent’s policy to a visit, and we’ll walk through what applies. Schedule a personalized tour of TerraBella Fayetteville, and let’s look at the numbers together.